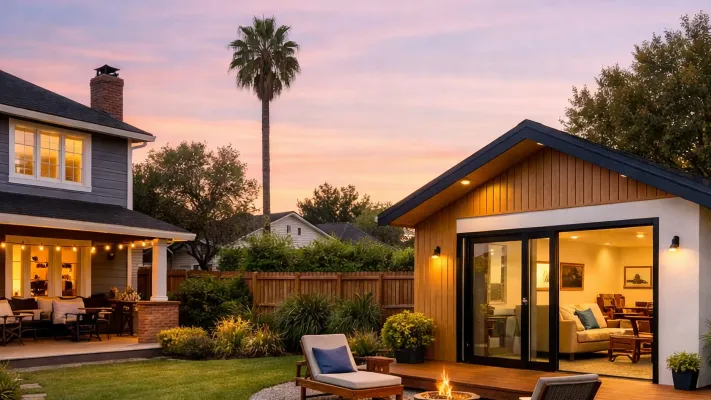
Thinking about building an accessory dwelling unit (ADU) on your property? Whether you want extra space for family, a private home office, or potential rental income, an ADU can be a meaningful investment. The big question for many homeowners is how to pay for it. While you usually cannot take out a separate traditional mortgage just for an ADU, there are several practical ways to finance one.
Understanding your options early can help you choose a path that fits your budget, timeline, and long-term goals. At Archstone Home Mortgage, LLC, we help homeowners make sense of financing choices so they can move forward with confidence.
Can You Get a Mortgage for an ADU?
In most cases, you cannot get a standalone mortgage for an ADU because it is considered part of your primary property rather than a separate home. Since the ADU is tied to the main residence, lenders typically view it as a home improvement or construction project instead of an independent real estate purchase.
That does not mean financing is out of reach. It simply means the funding usually comes through products connected to your existing home, available equity, or planned construction.
Common Ways to Finance an ADU
1. Cash-Out Refinance
A cash-out refinance replaces your current mortgage with a new, larger loan and gives you the difference in cash to use for your ADU project.
- Can provide a large amount of funding at once
- May work well if you have strong equity and solid credit
- Changes the rate and terms of your current mortgage
- Could increase your monthly payment
This option may be worth exploring if you want one loan instead of multiple payments, but it is important to compare the new loan terms carefully.
2. Home Equity Loan
A home equity loan lets you borrow a lump sum against the equity you have built in your home, usually with fixed monthly payments.
- Predictable payment schedule
- Useful for homeowners who know their project budget upfront
- Typically requires sufficient equity and good credit
- Adds a second loan payment alongside your primary mortgage
If consistency matters to you, a home equity loan can offer stability while you finance your ADU build.
3. Home Equity Line of Credit (HELOC)
A HELOC gives you a revolving line of credit secured by your home. This can be especially helpful for ADU projects where costs are paid in stages.
- Flexible access to funds as needed
- Can help manage changing construction expenses
- Rates are often variable, which can affect future payments
- Works best when you want borrowing flexibility
Because costs on construction projects can shift, a HELOC can be useful, but you will want to understand how rate changes could affect your budget.
4. Construction Loan
If you are building a detached ADU from the ground up, a construction loan may be an option. These loans are designed to fund projects in phases as work is completed.
- Often requires detailed plans and contractor agreements
- Funds are usually released in draws
- May involve stricter qualification standards
- Can be a good fit for larger or more complex ADU builds
Construction financing can be more involved, but it may align well with projects that require formal budgeting and staged disbursements.
5. Grants and Local Assistance Programs
Some homeowners may also qualify for state or local ADU grant programs. These programs can sometimes help with planning costs, permits, or portions of construction expenses.
- Availability varies by location
- Programs may have income, property, or occupancy requirements
- Funding can be limited
- May reduce your out-of-pocket costs
Because these programs differ widely, it is worth checking what may be available in your area before finalizing your financing strategy.
What to Consider Before Choosing a Financing Option
Before moving ahead, take time to evaluate the full financial picture. The right solution depends on more than just the interest rate.
- Your current mortgage rate and loan terms
- How much equity you have available
- Your credit profile and income
- Your estimated construction timeline and budget
- Whether the ADU will be used for family, work, or rental income
You should also account for permit costs, design fees, utility connections, maintenance, and any unexpected construction expenses that could arise during the project.
How Archstone Home Mortgage, LLC Can Help
If you are exploring ADU financing, speaking with a mortgage professional early can save time and help you avoid costly surprises. We can help you review your equity position, compare loan structures, and understand which options may fit your goals.
For personalized guidance, reach out to Archstone Home Mortgage, LLC at 206-992-4675.
Final Thoughts
An ADU can add flexibility and long-term value to your property, but choosing the right financing path is an important first step. While a separate traditional mortgage for an ADU is usually not available, homeowners often have several workable alternatives through refinance, equity-based borrowing, construction financing, or local support programs.
With a clear budget and the right lending strategy, your ADU plans can move from idea to action. If you are ready to explore your options, Archstone Home Mortgage, LLC is here to help you take the next step.